Michael McFadden: Building OptiFunder in Mortgage Finance
In this episode
- Yeah, sure. So what OptiFunder it's a fintech company that specializes…
- Yeah. I mean, and others that sat in my seat at…
- So it was a fast ride and really, I didn't have…
- And so in the world of business, it's very relevant and…
- My wife is a photographer. She's actually coming up to the…
- That, all of that data is sitting in the loan origination…
About the guest

Michael McFadden
Founder and CEO · OptiFunder
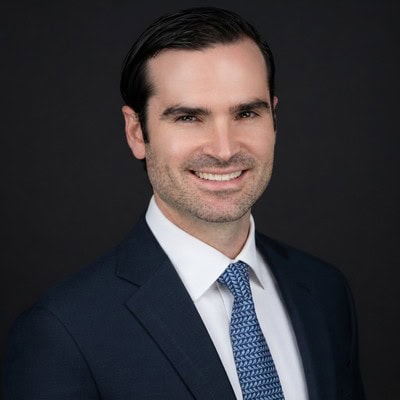
As a finance and strategy executive, Michael brings a very diverse set of skills to drive an organization forward. He's excelled in developing and leading many strategic plans to include raising capital, IPOs, and M&A from both the buy and sell-side. His Corporate Finance experience includes raising over $100 million through an IPO and leading a company sale process, culminating with a $211 million take-private sale.
Additionally, He's led the advancement of FP&A and Investor Relations organizations upon going public. Finally, he has a deep passion for capital markets and utilizing financial instruments and corporate finance to mitigate risk and maximize shareholder value. Beyond his background and experience, he has a unique ability to attract and promote the advancement of talent at all levels by fostering an achieving culture across the organization.
Read the transcript5,937 words
Brad BurrowHello. This is the In a World with Real Media podcast. I'm here with Mike McFadden from OptiFunder. Mike, thanks for joining us. I really appreciate you getting on the podcast with us.
Mike McFaddenAbsolutely. Yeah, it's a pleasure.
Brad BurrowYeah. So Mike, if you could just, let's start off. I'd love to, tell me a little bit about OptiFunder. I want to kind of get into as much as you're kind of willing to educate our listeners and me about what it is that you guys actually do, but give me the kind of the elevator speech, and then I'd love to get into your background a little bit.
Mike McFaddenYeah, sure. So what OptiFunder it's a fintech company that specializes in the residential mortgage industry, which is one that had a lot of moving pieces and changes since the crisis. And even before the crisis, that was a culprit for a lot of that stuff. So we provide technology to non-bank mortgage originators. And so there's two primary types of companies that will originate mortgages: there's banks and then there's non-banks. And actually, where we stand today, non-banks account for around 60 to 65% of all newly originated mortgages. So the market share has really transferred from bank to non-banks really post crisis. And a lot of it has to do with that's what they do. That's what they know. That's all they do.
Mike McFaddenAnd so they tend to be a little bit better at underwriting and processing and getting that loan closed rather than banks. However, given that they are a non-bank, they have to fund their business differently than a bank would. A bank has deposits and when they're funding a loan, meaning that wire showing up at the closing table for the borrower, they have deposits that they can use to do that. Non-banks don't. So what we do is we provide technology that optimizes which bank they should use. So the non-bank to use what are called warehouse lines. So we inform them which warehouse line they should use. And then we automate the process of actually requesting that loan to be funded to be that bank warehouse line.
Brad BurrowAnd based on what I was reading, that can change by the minute, right? I mean, is that the big thing with what you guys do is you're finding the best option based on that very minute?
Mike McFaddenYeah. It's ... We're, there's so much data. If you think about even as a consumer going through the mortgage origination process, all the data and pieces of information that's collected, well, that's happening. With a company they're doing thousands of loans a month, and so every loan is kind of moving all throughout that process, real time. And so what we do is we leverage machine learning and our direct integrations to those core systems to understand where loans are in the pipeline, what the probability is of them funding, the timing it's going to take to actually get them funded to make the decisions that I actually have to make today. Because those loans that are, that I'm making the funding decision on today are impacted by the loans that are coming down the pipe later in the month or loans that I've already funded or are being sold. So we can, with the use of technology, take into consideration all of that information that is obviously impossible for a human to do real time.
Brad BurrowYeah. And so that's the machine learning aspect of what you guys do?
Mike McFaddenYeah, I mean, the machine learning piece is more about any and all data that we're consuming, we're updating our assumptions, right?
Brad BurrowRight.
Mike McFaddenAnd so a, it's not a static model. It's always learning. So as data changes and as the ... So therefore, the algorithm gets smarter. It's always using all the information it consumes. So it's, there's been so much advancement in the world of machine learning that that has allowed us to do that. And we've just brought it to a piece, really in an industry, that it's kind of right for this use of the technology.
Brad BurrowAnd there's nothing out there that is like this, it sounds like. This is very new.
Mike McFaddenYeah. Certainly we are new and there's not, we don't have any direct competitors, right? So our direct competitors are the manual sub-optimized process that people have in place today and feel comfortable with it. But that's a competitor that I'm more than comfortable competing against.
Brad BurrowAnd there's no way that they can keep up with what's happening at the speed of things, of the way things happen in business right now is just that. Do you have any estimates on how much money is being lost because of not knowing what that is?
Mike McFaddenOh, sure. Yeah. I mean, we've done, even with our customers and prospects, what we do is we will perform a back test for clients, right? Completely free sometimes. And we'll say, "Hey, give us the information that, all the loans that you funded and sold over the last three months. We'll run it through our technology, tell you what our costs would have been compared to what the cost was that you actually incurred." And our results are showing that that savings ranges from two to three basis points on funded volume. So that may not sound like a lot, but the old adage in the mortgage industry is about squeezing basis points out of billions.
Brad BurrowYeah, yeah.
Mike McFaddenSo these guys are originating billions and billions of dollars of mortgages and they're focused on squeezing out a few basis points. And if we're able to drop two to three more basis points to the bottom line, that translates to a really big number.
Brad BurrowYeah. Big number, I bet, for like a Rocket Mortgage or somebody like that.
Mike McFaddenExactly.
Brad BurrowYeah.
Mike McFaddenYeah. Somebody like Quicken, Rocket Mortgage, they're, and I think in the first half of this year, funded $55 billion of newly originally mortgages.
Brad BurrowIn six months? Wow.
Mike McFaddenSo in the first six months, yeah.
Brad BurrowWow. That's amazing.
Mike McFaddenYeah. Yeah. As a non-bank. So it's pretty impressive.
Brad BurrowSo one point in a number like that is that's a lot of money.
Mike McFaddenYep.
Brad BurrowYeah, yeah. Amazing. So tell me about, so you started the company, did you found the company?
Mike McFaddenYeah.
Brad BurrowOkay.
Mike McFaddenI did, yes. Yeah.
Brad BurrowSo tell me, I'm really interested to get into that a little bit. It's like, how did you get the idea to do this? And then having an idea and actually executing on an idea are two different things.
Mike McFaddenYeah.
Brad BurrowSo talk us through that process.
Mike McFaddenSure.
Brad BurrowThat's amazing.
Mike McFaddenYeah. Well, the reason I started it was because I single handedly dealt with this problem myself. So I used to run finance at a large non-bank mortgage company and knew this problem existed because I dealt with it and it drove me nuts and I kind of tried to, while I was there, find a solution for it with the technology I had available to me and that I was capable of doing, which was Excel.
Brad Burrow[crosstalk 00:07:28] So you knew that you were losing money on deals?
Mike McFaddenOh, absolutely. Absolutely.
Brad BurrowYeah.
Mike McFaddenYeah. I mean, and others that sat in my seat at other companies that know it as well. And so since we've launched this, it's not been, we haven't had to spend a lot of time convincing people that there's a problem. They know. It's just the solution. So since the time I was at that company, which I was, I ran finance at Stonegate Mortgage for four years and left in May of 2017. And really, the first day after that is when I started to kind of put the plan together to launch OptiFunder. I will tell you, and you said, the comment you made about actually executing on that plan-
Brad BurrowYeah.
Mike McFaddenThat there were multiple times where I'd hit roadblocks and I said, "Oh my gosh, I didn't even think about that." I didn't think about curtailments or I didn't think about the ability to transfer loans. I didn't think about all these ... And so the way I kind of explained it is you always peel back these layers of the onion and it's you kind of make the decision, "Okay. Is that a layer that that is just too much to overcome or is there, can I build a solution around that?" So OptiFunder is two plus years in the making, right?
Brad BurrowYeah.
Mike McFaddenSo that was 2017. We didn't actually publicly launch it until June of this year. And so-
Brad Burrow[crosstalk 00:09:01] So you've been building the algorithms and all of everything for that whole time? Yeah.
Mike McFaddenOh, for sure. And that, we, the amount of meetings and people that I've reached out to and during that time, I relocated from Indianapolis to St. Louis and had to build a network here in St. Louis. And certainly very fortunate of where, of St. Louis, with the strong universities.
Brad BurrowYeah.
Mike McFaddenAnd a lot of people in this area have machine learning and optimization experience, but you don't find a lot of places. And so I was very fortunate that we had that skillset here in St. Louis. And I don't even want to think about the number of Starbucks meetings I've had with people that, to talk about this idea over that two and a half years.
Brad BurrowYeah.
Mike McFaddenBut I spent a lot of time and effort into it, but it's been two plus years in the making, so it's not been an easy road for sure.
Brad BurrowSo did you have any like development background or anything like that when you took this on or you just went into and said, "I need to find people that can help me build this?"
Mike McFaddenYeah, no. I didn't. So I knew the problem. I knew how, I think, to formulate a solution. I didn't, I couldn't solve it myself, right?
Brad BurrowYeah.
Mike McFaddenI didn't have, I don't, I'm not a developer. I'm not a programmer. I don't ... I have, I consider myself pretty skilled mathematically. I have an undergrad in physics, not that stuck with me. I'm certainly more in finance now.
Brad BurrowYeah.
Mike McFaddenBut so I can understand it. I couldn't do it. So I had to, that's why I say it's all these meetings at that Starbucks and places to find the right people. So I mean, that's the hardest part in this whole thing is finding the people that compliments the lack of skills that you have and going in and then building from there.
Brad BurrowYeah, true startup sounds like, huh?
Mike McFaddenOh yeah. Yeah. No doubt.
Brad BurrowOne of the things I wanted to ask you about, too, is you actually took your previous company public, didn't you, the mortgage company?
Mike McFaddenYeah. So yeah-
Brad Burrow[crosstalk 00:11:20] Did you take it through that process?
Mike McFaddenYeah. So that's what got me into the mortgage industry. So I didn't know how to spell mortgage before 2013 when Stonegate had reached out to me about coming in and really and leading internally the IPO process. And again, Stonegate was a story of taking advantage of this market dynamics and really the bank kind of exiting the space and therefore, the opportunity for non-banks. And Stonegate was able to grow very rapidly through that. And so yeah. I came in May of 2013. Didn't know the first thing about mortgage and had to just kind of ingulf myself in other public filings of other mortgage companies and try to learn and work with the investment bankers and the sell side analyst. and we were ringing the bell in October of 2013.
Brad BurrowYeah.
Mike McFaddenSo it was a fast ride and really, I didn't have any other option once I came on. I had to figure it out. And so, and I think I benefited from that lack of history as well, right?
Brad BurrowYeah.
Mike McFaddenI didn't have any biases coming into the mortgage space. It didn't matter how things were done previously. I wanted to find current solutions to the problems that were out there. And that's really kind of how OptiFunder came to be is there a way for us to bring technology and automation to a suboptimal manual process?
Brad BurrowDo you think that you would have moved forward with OptiFunder without the experience of taking a company public? I mean, that seems like a pretty good foundation of skills to be able to start a company.
Mike McFaddenYeah. Because, but look, it was a very different stage. So the short answer is yes, but because the conversations in the institutions that you meet with on an IPO roadshow are certainly very different than the groups that I've just recently met with on raising our seed round. And so that story is very different. And so I'm not sure that being able to tell the story and put a deck together and go and execute on a plan, very valuable, but I'm not sure that had we gone public or not, that would've stopped me from pursuing OptiFunder.
Brad BurrowYeah. Another thing that kind of sparked my interest is in something I've seen in commercial lending too, is the banks have gotten away from commercial lending a lot. There was a period after the economy crashed that you couldn't get a loan. You couldn't finance. Like I own my commercial building and well, I can't tell you how many times I tried to refinance. There's no way that that was going to happen. It's changed a little bit recently it seems like.
Mike McFaddenYeah.
Brad BurrowBut the whole industry changed as a result of that. Do you think that that kind of opened up some opportunities for you?
Mike McFaddenWell, I think really the opportunity was that ... yeah. Because look, our core customer is a non-bank originator, right? And the dynamic that occurred in the market and at the banks really saying, "The unknown and the risk involved in being a residential mortgage origination is just too high to be in a same capacity we've been in it previously." Now they can't get out of it completely.
Brad BurrowYeah.
Mike McFaddenYou have people walk into your branch and want a mortgage, right? You have to offer it as a bank, but you can kind of choose to be in it the way you want to be in it. And that just opened up the doors to non-bank, that we're funded differently with other kind of more private capital, a lot of single owners or small ownership groups that own large non-bank originators, right?
Brad BurrowYeah.
Mike McFaddenYou got Quicken loans. You've got, you have Dan Gilbert that owns that. You got groups like United Wholesale. It's owned by kind of one guy. So there's these big, big groups that really found a way to perfect that as much as possible, that origination process, and really specialize in doing one thing. And that's residential mortgage origination. And so those guys being non-banked, that shift, and now the market being 60, 65% comprised of non-bank, that's a huge opportunity for us.
Brad BurrowYeah. So talk a little bit about your background. Where did you grow up? I'd love to hear a little bit of personal history.
Mike McFaddenYeah.
Brad BurrowYeah. Are you from the Indianapolis area? Is that original ...
Mike McFaddenYeah. Yeah. So grew up in Indy. I was born in Michigan, but moved to Indianapolis at a young age. And so really Indy was everything I knew. Was ... I went, obviously went to high school, south side Indianapolis. Went to college at a school in Indianapolis, University of Indianapolis. Played baseball there for four years.
Brad BurrowIs that right?
Mike McFaddenLike I said ... yeah. Like I said, graduated with a physics degree and then went on to do my MBA at IU.
Brad BurrowA baseball player with a physics degree? That doesn't add up man.
Mike McFaddenYeah. Not common, but I was a pitcher. So pitchers aren't that normal anyway.
Brad BurrowYeah.
Mike McFaddenBut yeah. Not a lot of physics majors, I'm sure, playing baseball.
Brad BurrowYeah.
Mike McFaddenLook, I saw baseball is something that I, like we were talking before this about the playoffs right now. I mean, I'm a huge, huge baseball fan and I saw it as way to get a free education.
Brad BurrowYeah.
Mike McFaddenEarly on, I probably had aspirations of going further, but when my college career was over and I knew that was it for me. And it's something that ... Look, I think that's something that has really stuck with me. Being a pitcher, you learn how to compete. It's you against the batter.
Brad BurrowThat's right.
Mike McFaddenAnd so in the world of business, it's very relevant and being a leader. Having people buy into what you're doing and leading by example and with hiring people in business. So there's a lot of similarities between competing on a athletic field and then and competing in the world of business.
Brad BurrowInteresting side note, there's a company here in Kansas City called Athlete Network and they believe that if you've been a college athlete or really high school, but college and beyond that, you have a skill set no matter what your actual schooling is that you have a skill set that employers want. So American Express, Enterprise, companies like that, work with them to recruit out of, when somebody's gone through college, people to come into their workplace. It's pretty interesting that.
Mike McFaddenYeah.
Brad BurrowSo you would probably be, you'd be in agreement on that probably.
Mike McFaddenOh, absolutely. Yeah. I mean, it's not easy. I mean, there's, going through someone's athletic career from an early age and it's getting through high school or college, that you have ample opportunities to quit. And you can decide whether the hard work is worth it and you want to put it in and work when others aren't. And so I agree. It's a mentality that you can't teach, I don't think. It's you're either are born with it and you try to pursue that or you don't. And that mentality is very well, I think, sought after in business.
Brad BurrowYeah. One thing that when I've kind of studied what you're doing a little bit with OptiFunder, I feel like it has the potential to be an industry disruptor. And I hear a lot of, we have a pretty big startup community here in Kansas City and a lot of people talk about what ideas are going to be industry disrupters because those are going to be the big ones. Would you agree with that? I mean, does this have the potential to really change the way business is done in the mortgage industry?
Mike McFaddenYeah. Well look, I think what it does, I'm not sure if it changed ... The mortgage is still going to be originated between a home buyer and in a company. I think what we do is I think it disrupts a piece of that process and a piece that is very costly and manual and has an opportunity for manual error. And certainly, if we can provide that solution to the, very much disrupting a piece of that equation. Now are we, do we have aspirations of moving into, further up the value chain of getting into loan origination and point of sale and all this stuff that, there are so many companies focused on that and they're going to be much better at doing that than we are.
Mike McFaddenWell, we're just focused on this core piece of a loan is funded in a warehouse from anywhere from 10 to 30 days. That 10 to 30 days is what we are solely focused on. How do we produce the most, the highest return for our customers when that loan is in the warehouse for that 10 to 30 days? That's really our focus, but can we disrupt the way it's being done today? Absolutely. I mean, I think we're already well on our way to doing that.
Brad BurrowWhy ... What would be the barrier to somebody saying yes to working with you? I can't, I mean, there's no reason to say no.
Mike McFaddenYeah. We've been fortunate enough to build a pretty strong pipeline early on. Look, the unknown, right? It's technology and some people maybe have a somewhat of a caution towards that, but I think more and more it's people understand that the value of technology and allowing you to really be a low cost provider, which is really what you have to be in this space, right? A mortgage is a commodity, right?
Brad BurrowYeah.
Mike McFaddenYou can get a mortgage anywhere. And so the guys that win are the guys that control costs the best and have had the lowest marginal costs to originate a loan. That's what we're trying to do.
Brad BurrowYeah.
Mike McFaddenSo yeah. Look, we haven't gotten a lot of pushback. People, like I said, if people have sat in the seat that I've sat in previously, they know this is a problem then and they're interested in hearing us out and giving us a shot. So we've been very excited with the early traction we've gotten.
Brad BurrowMan, it's amazing. I can't imagine a competitor that has that and another competitor not wanting it if they, helps them to compete.
Mike McFaddenYeah.
Brad BurrowIt's like that competitive advantage, you're two or three points is a big deal. Right?
Mike McFaddenThat's exactly. Exactly. So that can mean companies that make it and companies that don't.
Brad BurrowYeah.
Mike McFaddenBecause there's ... In this business, there's a high amounts of leverage clearly because the way these non-banks fund on their business. And secondly, the margins are pretty thin and you have to focus on cost and revenue is really something in this business. Being a commodity, it's really a lot of times, out of your control, right?
Brad BurrowRight.
Mike McFaddenThe things you can control is on the cost side of the equation.
Brad BurrowYeah. Yeah. So I want to switch gears just a little bit. I was kind of looking at your LinkedIn profile and what caught my eye was this company called ShuttrPlace.
Mike McFaddenYeah.
Brad BurrowI'm like, "What?"
Mike McFaddenYeah.
Brad BurrowThat's like a total different direction from the all the other things you could done. What was the, what's the story on that?
Mike McFaddenYeah. You know what's interesting is that's actually how I met my wife actually.
Brad BurrowIt was fate then, right?
Mike McFaddenYeah. For building ShuttrPlace. And so what's been great about that was let's really learning kind of how to, how do you, what are all the things you got to do as a startup? How do you put a business plan together? How do you execute it? How do you find talent? And so there's some similarities, right? It was a kind of a marketplace type concept of how do we better connect consumer searching for a photographer to those photographers.
Brad BurrowYeah.
Mike McFaddenMy wife is a photographer. She's actually coming up to the office today to take head shots for up for all of us to get those updated.
Brad BurrowYeah.
Mike McFaddenAnd so it was a great run, that working with developers and kind of understanding the lingo of developing a software and all the things to watch out for. And again, with what we're doing at OptiFunder, there's two parties involved, just like a photographer and a consumer looking for a photographer. There's a non-bank originator and then there's the resulting bank or warehouse lender.
Brad BurrowYeah.
Mike McFaddenAnd what we're doing is better connecting them. We're making a decision for an originator and then we're more efficiently and effectively connecting them to that warehouse lender. So there's a lot of similarities in that. And so great, great learning experience and been fun to kind of help with that.
Brad BurrowIs that still going now?
Mike McFaddenYeah. So it's ... I'm not involved in it much anymore. And so we ... I had to step away from that, obviously, with my focus on OptiFunder. But yeah. We're still working on it and it's been a little bit different kind of trajectory than OptiFunder certainly has. But I think the learning experience has been much more valuable than anything else.
Brad BurrowSo what are your biggest challenges moving forward right now? And I know you're still in kind of startup mode. You're actually marketing and selling right now, right? I mean, you're-
Mike McFaddenYeah, yeah.
Brad Burrow[crosstalk 00:26:31] What are the challenges you have?
Mike McFaddenYeah. It's anytime you're going in and implementing a new technology, it's getting that implementation process perfected and implementing it as quickly as possible, but then also implementing it successfully. So we're at that phase where we've got deals that are closing now and moving on to the implementation phase, working with our partners, not necessarily on selling them on the concept and on the solution, but going and delivering it, right? So you've kind of turned the page and now it's about going and executing on what you told them that you can do. Is that a challenge? Yeah. I think it's more of an opportunity, right?
Brad BurrowYeah.
Mike McFaddenWe've been successful in implementing this thing and demonstrated the savings and the power of it. So really we're excited that to just get more eyes on it, get people talking about it more. There's a big industry conference coming up here and a couple of weeks down in Austin. That's kind of our coming out party really. We'll be exhibiting there and have packed schedule of meetings and then we'll have a booth. And so super excited, really just on getting people's, more people's eyes on it. And once you get it in there, you're going to get customer feedback. You're going to then say, "Oh hey, that'd be great if you could do this" or "Have you thought about this?"
Brad BurrowYeah.
Mike McFaddenThat helps build our product roadmap better than us sitting in a room and talking about the things that we think would be interesting. We start actually hearing from customers and they start to build that roadmap for us.
Brad BurrowThat's kind of why I was going to ask you is do you do beta testing? I mean, you almost need Quicken or somebody like that to really kind of work out the bugs and beta tests the process. Did you do anything like that?
Mike McFaddenYeah. So we did that before even launching it, right?
Brad BurrowOh, okay.
Mike McFaddenWe had a beta customer and that we implemented from really from March to May of this year. So that was our opportunity to get it in, get real data on it, connect it with systems and get feedback there. So yeah. Certainly you need with a technology like this, you need to beta test it. And we did that and got great feedback and enhanced it and made some tweaks to it. So it's been a pretty fun ride from concept to building it in a very demo friendly system to converting it into a full software and then getting it implemented and now moving everything into production. So yeah.
Brad BurrowAnd you're having to implement this into, I would think, into a company's process too, right? I mean, that's got to be a challenge. I mean, everybody has a different software platform. I mean, that has got to be, and you're going to have people on staff to do that 24/7, I would think.
Mike McFaddenYeah. Yeah. So the core system that mortgage companies use is called a loan origination system or LOS. And so there are a handful of providers of loan origination software that we integrate directly with. And so we've already kind of solved that piece of it.
Brad BurrowOkay.
Mike McFaddenBut the process piece, to your point, is sitting down with a company and saying, "Okay, walk us through this process you're currently doing today of manually extracting all this data out of the LOS, going and logging in to these different systems, and taking that file and manually uploading it and then running a report." All this manual repeatable stuff that's being done today, really what we're doing is saying, "Okay, that you no longer have to do. We have replicated all of that and automated it in our system." And so the process piece of it is really, we're removing steps of the process because our software automates it for our customers.
Brad BurrowYeah. Is all of the data ... Another question that as I'm learning about this, is all of that data that the machine learning is using to bring back a result, is that readily available? I mean, how do you get to all of that data?
Mike McFaddenThat, all of that data is sitting in the loan origination system. So that's our, we directly integrate with a loan origination system and essentially import that data into our system to able to run their-
Brad Burrow[crosstalk 00:31:13] So it's already there and available then?
Mike McFaddenSo it's already there. Yeah, yeah.
Brad BurrowOkay.
Mike McFaddenYep.
Brad BurrowYeah.
Mike McFaddenBut again, today without OptiFunder, it's sitting there not being used in the warehouse decision. And so we're essentially taking it from a spreadsheet and bringing it online and integrating it and connecting it to the loan origination system, which the loan origination system is really designed to get you to closing a mortgage, right?
Brad BurrowOkay, yeah.
Mike McFaddenWell, that's great, but then the very next thing that needs to happen is the loan's got to get funded, meaning money needs to show up at the closing table, right?
Brad BurrowYeah.
Mike McFaddenFor that borrower to buy his house.
Brad BurrowRight.
Mike McFaddenAnd so what we essentially do is via our integration is extend that loan origination system into the funding transaction. So that's the piece we're performing. And today that's being done by extracting all that data out of the LOS, putting it in a spreadsheet, and then sending it to the back. We're better connecting the warehouse lender to the originator via our software now. So that manual extraction of data and then you lose all connectivity to the loan origination system is now gone. We continue that connection once the loans actually in that, in the warehouse
Brad BurrowAnd time savings, that's got to be a huge time saving too, right?
Mike McFaddenOh huge. Yeah. I mean, another way saying that as efficiency gains, right?
Brad BurrowYeah.
Mike McFaddenSo now a funder can significantly increase the amount of loans that they can fund in any given day. And, and the accuracy of those loans, of the loan being founded is substantially improved as well.
Brad BurrowSo not only are they more efficient, they're closing more loans, but they're also getting two or three points.
Mike McFaddenExactly.
Brad BurrowI mean-
Mike McFaddenExactly, yep.
Brad BurrowI want to go to sales. I want to be in sales for you. That seems like a no brainer.
Mike McFaddenYeah.
Brad BurrowI'll just move up. I'll still like the Royals though. I just want you to know that.
Mike McFaddenBut yeah. That's right. Like I said, I'm not, I'm one of the few that are not a Cardinals fan here in St. Louis but-
Brad Burrow[crosstalk 00:33:23] I don't want to date the pod ... yeah. I don't want to date the podcast, but the Cardinals are a little bit in mourning today.
Mike McFaddenYeah.
Brad BurrowSo we've been watching. I was going to tell you, too, my son is a pitcher at a Hannibal-Lagrange, which is just North of St. Louis, about an hour and a half in Hannibal, Missouri. So-
Mike McFaddenYeah, no. That's great.
Brad BurrowSo we're kind of going through that. We've gone through all the baseball stuff and you're spot on. I just think there's so much you can learn from baseball especially. There's just so many ups and downs and adversity and how you overcome adversity and it's awesome game.
Mike McFaddenYeah. One of the things that has always stuck with me from, you know, I think it was my high school coach had told me this is, the reason baseball is the greatest game in the world is that no matter what the score is, no matter how much you're down, how much you're win, you still got throw the ball over the plate. There's not a clock that's going to stop the game, right?
Brad BurrowYeah.
Mike McFaddenYou can't just sit on the ball and run the clock, yeah. You got to get up there and throw the ball over the plate. So it teaches you a lot about dealing with adversity and continuing to compete no matter how bad the situation is.
Brad BurrowAnd it's so relevant to business. It's exactly like business.
Mike McFaddenAbsolutely.
Brad BurrowYep.
Mike McFaddenAbsolutely.
Brad BurrowIt's like, yeah, you might've given up a home run, but come back and get them next to inning. That type of thing.
Mike McFadden[crosstalk 00:34:44] That's right.
Brad BurrowSo let's wrap it up here. Last thing I want to ask you a little bit about the future. What, I mean, I know things are moving so fast in your world, but couple of years out, a year out, maybe five years, what do you see for OptiFunder and what you guys are going to be doing?
Mike McFaddenYeah. Like I said, I think for us, we're so focused on improving that 10 to 30 days that that loans are in the warehouse. And so I think our focus is on working with more integration partners, bringing more data into that that's relevant to that decision. Whether there's document custodians, that is kind of another piece of the process, making the loans being bought off in the warehouse line, making that process more efficient and automated for our customers. And then potentially industry expansion as well, right?
Brad BurrowYeah.
Mike McFaddenThis is real for, this was what I saw as an opportunity in the mortgage industry, but there's a lot of other non-bank financial lending institutions. Whether it's consumer lending or auto lending or those types of things that any institution that this is using banks as for short-term kind of working capital lines or revolving credit lines. I think there's an opportunity for us to look at those things too. So I think there's an opportunity for us to expand this into other industries, but right now, the opportunity for us and mortgage is so high that that's really what we show up to work every day thinking about.
Brad BurrowAnd that's a big market. [crosstalk 00:36:33] That's only going to increase.
Mike McFaddenThere's $11 trillion of mortgage debt outstanding.
Brad BurrowYeah, I believe it.
Mike McFaddenThis year alone, we will, the market will be probably close to $2 trillion of newly originated mortgages. I mean, that's a huge number. If we can squeeze out a couple of basis points out of that, we're providing a huge ROI to our customers.
Brad BurrowI'll just take one of those, if you want to send that over to Kansas City.
Mike McFaddenThat's a lot of zeroes.
Brad BurrowYeah. You can knock a couple zeros off, I'd still be happy.
Mike McFaddenYeah, yeah. Exactly.
Brad BurrowWell, that's great. Well Michael, I really appreciate you being with us. If somebody ... I mean, who knows who could hear this, if somebody wanted to get in touch with you, how would they do that? What would be a good way to get in touch with you? Maybe they want to invest?
Mike McFaddenYeah. Yeah, you can check out our website optifunder.com. My email is michael@optifunder.com. So we're available and would love to chat with folks.
Brad BurrowWell, I appreciate you being on here and best of luck to your show coming up here and, man, I see a very bright future for you guys. It's really awesome.
Mike McFaddenAbsolutely. And I appreciate it. It's been a pleasure to spend some time chatting with you.
Brad BurrowAll right, this is the In a World with Real Media podcast. Thanks for joining us. Check us out on iTunes, Spotify, all the podcast formats and if you know anybody who would like to be on our show, let us know. Thanks Mike. Appreciate it.
More episodes
Next in the series

Let’s talk
Make your own podcast
Record, edit, syndicate and create social media cuts, from the room this episode was made in. Hosted shows, guest interviews, audio or video: the room and the crew are here.